Customs valuation determines the value customs authorities use to assess value-based import duties. Transaction value is usually the starting point, but the commercial invoice amount is not automatically the final customs value.
What Is Customs Valuation?
Invoice value is the amount shown on the supplier’s commercial invoice. Customs value is the value determined under the destination’s rules for ad valorem, or value-based, duties. Landed cost includes the costs of getting the goods to their final destination, including charges beyond the customs value.
A declared value is the figure submitted on a customs entry; authorities may review the supporting records before accepting it.
How Do the Six Customs Valuation Methods Work?
The six World Trade Organization (WTO) customs valuation methods follow a prescribed sequence. Customs considers a later method when an earlier one cannot establish an acceptable value.
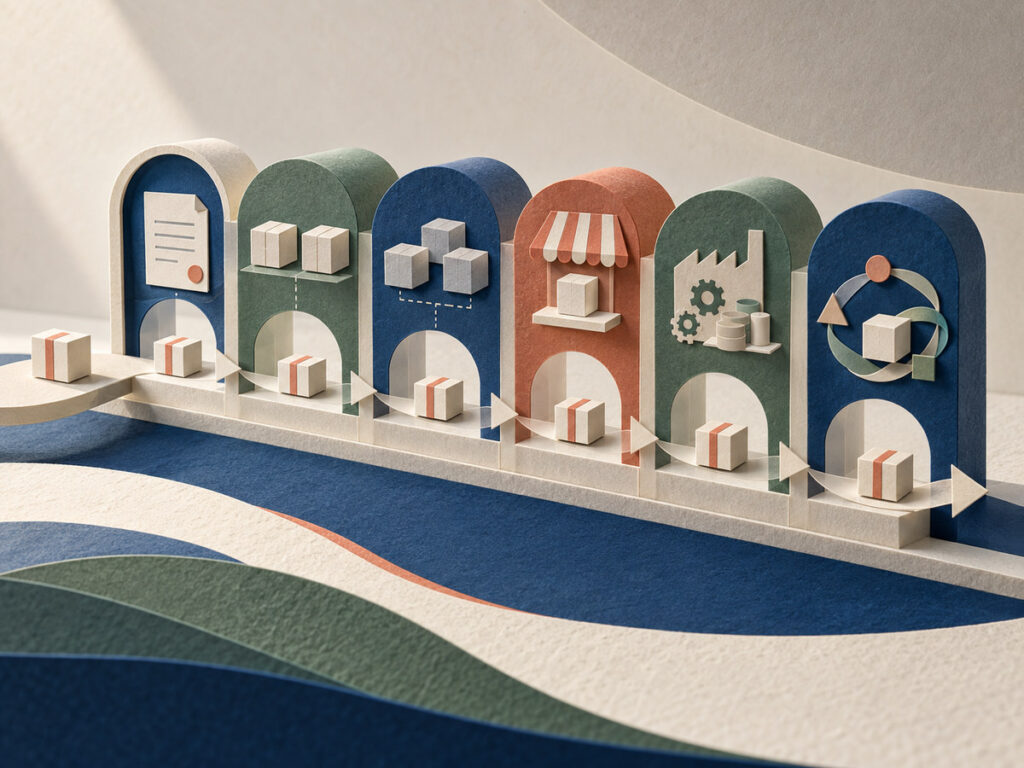
| Order | Method | When it becomes relevant |
|---|---|---|
| 1 | Transaction value | There is a qualifying sale for export, and the price paid or payable can be supported and adjusted as required. |
| 2 | Transaction value of identical goods | Method 1 cannot be used, and suitable values for identical goods exported to the same destination are available. |
| 3 | Transaction value of similar goods | Methods 1 and 2 cannot be used, but suitable values for commercially comparable goods are available. |
| 4 | Deductive value | Earlier methods fail, and a qualifying sale price in the importing country can be adjusted for relevant post-import costs and margins. |
| 5 | Computed value | Earlier methods fail, and reliable producer data supports the cost of production, profit, and relevant expenses. |
| 6 | Fall-back method | The preceding methods cannot be applied, so customs uses reasonable means consistent with the valuation framework. |
The WTO framework permits methods 4 and 5 to be reversed at the importer’s request, subject to the destination’s rules. The importer and broker should record why an earlier method cannot be used.
When Does Transaction Value Need Review?
Review transaction value when the invoice omits buyer-paid inputs or other payments, or when the sale itself may not qualify. Destination rules govern any adjustment.
Buyer-Supplied Assists and Packing
Tools, molds, materials, or design work supplied by the buyer free or at a reduced cost may add value that the factory invoice does not show. Purchase and transfer records, production agreements, and cost allocations show what the buyer supplied and how the cost relates to the imported goods. Local rules determine which inputs qualify as assists and how to allocate their value.
Packing and container costs can also affect transaction value when the buyer bears them and the price excludes them. Packaging invoices and contract terms show who paid these costs.
Commissions, Royalties, and Resale Proceeds
Selling commissions, some royalties or license fees, and proceeds returned to the seller after resale may require additions. Buying commissions have different treatment under the WTO framework. Agency agreements, payment records, license terms, and resale arrangements show what each payment covers. Check each payment against the sale terms and invoice before adding it to customs value.
Related-Party Sales
A buyer-seller relationship does not automatically disqualify transaction value. The question is whether the relationship influenced the price. Give the destination broker the intercompany agreement, pricing policy, and comparable sale records for that assessment.
Freight, Insurance, and Incoterms
International freight and insurance may be included or excluded under the importing country’s valuation rules. An Incoterm helps identify who pays each charge, but it does not decide the customs value on its own. Give the broker the sale contract, named Incoterm and place, freight quote, carrier invoice, and insurance invoice. These records show which charges the seller’s price includes and which were billed separately.
Goods Without a Sale
Gifts, free samples, leased goods, and consignment stock may lack a qualifying sale for export. A zero-price or nominal invoice does not establish a zero customs value. Gather the transfer agreement, ownership records, product description, and available comparable sale or cost data. The destination customs professional should identify the first method that can be applied.
Which Documents Support a Customs Value?
The commercial invoice states the seller’s price. Supporting records show what that price includes and whether customs value needs an adjustment.
| Record | What it helps establish |
|---|---|
| Commercial invoice | Stated price, currency, buyer, seller, goods, and sale terms. |
| Purchase order or sales contract | The agreed sale, payment terms, and what the price covers. |
| Proof of payment | Amounts paid or payable, including payments outside the invoice. |
| Packing list | Whether the quantity and goods match the invoice and shipment. |
| Freight and insurance invoices | Whether transport and insurance were charged separately or included in the sale price. |
| Royalty or license agreement | The link between license payments and the imported goods or their sale. |
| Commission agreement | Who the agent represents and what the fee covers. |
| Records for buyer-supplied assists | Who paid for molds, materials, or design work and how the cost relates to the goods. |
| Related-party pricing records | How the intercompany price was set and whether the relationship influenced it. |
Keep the records for the specific shipment and any adjustments, using the destination’s retention rules. For cargo from multiple suppliers, reconcile the quantity, currency, parties, and terms for each sale, even if the goods share one freight booking.
What Makes Customs Question a Declared Value?
Customs may question a declared value when records conflict or material payments are missing. A low price alone does not prove an error, but an unexplained gap in the records needs review.
- Records conflict on price, currency, or Incoterm.
- A nominal price or goods without a sale lack supporting records.
- Related-party pricing, assists, or separate payments lack support.
- Freight or insurance is not split from goods when required.
- A prior method is reused for different goods or sale terms.
- Landed cost, retail price, or a quote is declared without support.
If a discrepancy appears, pause the final filing instructions and assemble the underlying records. Ask the importer of record and destination customs professional to resolve the value before the entry is submitted.
What Should Importers Do Before Filing?
Prepare a transaction file for the destination broker before the customs entry is submitted.
- Confirm the buyer, seller, importer of record, goods, currency, and sale for export.
- Match the invoice to the contract, payment record, and packing list.
- Identify buyer-supplied inputs, commissions, royalties, related-party terms, and resale proceeds.
- Separate goods, freight, insurance, and post-import charges where the documents allow it.
- Ask the destination broker or qualified professional to confirm the method, adjustments, exchange rate, and evidence required locally.
How Can Foresmart Help With the Document Handoff?
For China-origin shipments, Foresmart can compare the commercial invoice, packing list, transport documents, and booking details for inconsistencies. Its team can request missing documents from suppliers and pass the available file to the destination customs partner.
Share the origin, destination, cargo details, Incoterm, and available transaction documents. Foresmart can plan sea, air, or door-to-door shipping while the importer and destination customs professional confirm the applicable valuation treatment.
Frequently Asked Questions
Can a Supplier Discount Reduce the Customs Value?
A supplier discount may affect customs value if it changes the price actually paid or payable and qualifies under the importing country’s rules. Keep the sales agreement, invoice, credit note, and payment record, especially if the price changed after import. Ask the destination customs professional whether the discount can be reflected in this shipment’s declared value.
Which Exchange Rate Should an Importer Use for Customs Valuation?
Use the exchange rate published by the competent authority in the importing country when currency conversion is required. The authority’s date rule may differ from the payment date, so ask the destination broker which rate applies to this entry.
Can an Importer Obtain an Advance Customs Valuation Ruling?
Some customs authorities offer advance valuation rulings for a proposed import transaction. Ask the destination customs authority about eligibility and required documents before import.